

Welcome Back, Fellow Parent
Let's start with a confession we've all made at some point:
"I know it's too much, but I just want them to have a great time."
Maybe it was the birthday party that somehow needed a bounce house, a taco truck, and custom goodie bags. Maybe it was the travel team, the private lessons, the $180 sneakers, or the Christmas morning that looked like a toy store exploded in your living room.
None of those things are bad. But somewhere along the way, a lot of us started measuring "good parenting" in dollars. And that's getting expensive.

Nobody hands out trophies for spending the most on your kids. But judging by our bank statements, a lot of us are competing for one anyway.
The Baseline Is Already Brutal
Before we even get to the extras, raising a kid is expensive on its own. According to recent reporting, the cost of raising a child in the U.S. has now topped $300,000 for the first time, and that doesn't even include college.
So when guilt and comparison start stacking "extras" on top of that number, it adds up fast.
The "Good Parent" Tax
Here's where the pressure to be a "good parent" tends to show up in our spending:
Where It Shows Up | What We Tell Ourselves | The Upgrade Cost (per year) |
|---|---|---|
Birthday parties | "Everyone else had a bounce house." | $300–$1,500 |
Youth sports | "If they don't play travel ball, they'll fall behind." | $1,000–$5,000+ |
Holidays | "It's only magical once." | $500–$2,000 |
Clothes and shoes | "I don't want them to feel left out." | $300–$1,200 |
Tech and phones | "All their friends have the newest one." | $300–$1,500 |
Extracurricular overload | "They need every opportunity." | $1,000–$4,000 |
Tutoring and test prep | "I can't let them fall behind." | $500–$3,000 |
Vacations | "We need to make memories." | $1,000–$5,000 |
"Pinterest" moments | "It has to look perfect for the photos." | $200–$800 |
You don't need to be doing all of these for the math to hurt. Just a few upgrades can easily add $3,000 to $10,000 a year on top of what raising a kid already costs.
The Three Forces Draining Your Wallet
After talking with a lot of parents (and looking honestly at my own spending), I think the "good parent" tax comes from three places.
😔 1. Guilt
This is the big one.
Working-parent guilt: "I'm not around as much as I want to be, so I'll make it up to them."
Childhood guilt: "I didn't have this growing up, and I want better for my kids."
Circumstance guilt: Divorce, a move, a tough year. Buying things feels like a way to make it right.
Here's the hard truth: you can't buy your way out of guilt. The toy gets old in a week, and the guilt comes back. What kids actually remember is time, attention, and how home felt. That doesn't show up on a credit card statement.
The KMONEY move: When you feel the urge to spend out of guilt, pause and ask, "Am I buying this for them, or for me?" If the honest answer is "for me," swap the purchase for time. A Saturday morning pancake date costs $12 and your kid will talk about it for years.
👀 2. Comparison
We used to compare ourselves to the neighbors. Now we compare ourselves to hundreds of parents on social media, many of whom are posting their highlight reel (and some of whom are quietly financing it).
The other family's Disney trip.
The birthday party with a professional balloon arch.
The parents on the sideline wearing the $90 team jackets.
The group chat where everyone "just signed up" for the summer camp that costs more than your mortgage.
Comparison is sneaky because it doesn't feel like spending pressure. It feels like normal. But "normal" in your feed isn't normal in real life, and you have no idea what's behind anyone else's spending. Plenty of those Instagram-perfect families are carrying debt, stress, or both.
The KMONEY move: Compare your family to your own past self, not other families. Are you saving more than last year? Paying down more debt? Spending more time together? That's the only scoreboard that matters.
And if social media is fueling the pressure, mute the accounts that make you feel behind. Your wallet will thank you.
😰 3. Fear of Missing Out (On Their Behalf)
This one feels the most responsible, which is why it's so dangerous.
"If they don't start travel soccer at 8, they'll never make the high school team."
"If they don't do test prep, they won't get into a good college."
"If we don't do every activity, they won't find their thing."
Parents are spending thousands chasing scholarships, opportunities, and "advantages" that may or may not ever pay off. And kids often end up overscheduled, burned out, and less interested in the very thing we paid for.
The KMONEY move: Before signing up for anything expensive, ask your kid one question: "Do you actually want this?" Then ask yourself: "Would I still do this if no other parents knew about it?" If both answers are yes, go for it. If not, save your money.

What It's Really Costing You
Here's where it gets real.
Say your family spends an extra $2,000 a year on "good parent" upgrades that nobody really needed. If you invested that money instead, at a 7% average return, over 18 years it could grow to about $72,000.
Bump that to $5,000 a year, and it could be about $179,000.
That's a college fund. Or a down payment for your kid someday. Or a much more comfortable retirement for you.
(Returns are hypothetical and never guaranteed, but you get the point.)
The Retirement Trap
And here's the part that really worries me.
The "good parent" pressure doesn't stop at 18. In a recent Bankrate survey, more than 3 in 5 parents of adult children said they've made financial sacrifices to help their kids. And 37% said they've sacrificed their retirement savings to do it.
I get it. We love our kids. But remember the airplane rule: put your own oxygen mask on first.
Your kids can borrow for college. They can get a job, a roommate, or a cheaper car. You can't borrow for retirement. And the most expensive thing you could ever do to your kids is become financially dependent on them when they're raising families of their own.
Sometimes the most loving financial decision is protecting your own future.
What Kids Actually Need
Here's the good news: kids are pretty simple.
Ask most adults about their favorite childhood memories, and you'll rarely hear about the most expensive gift they got. You'll hear about:
The camping trip where it rained and everyone laughed about it.
Dad making pancakes every Saturday.
The board game nights.
A parent showing up to every game, even the ones they lost.
Feeling safe, loved, and paid attention to.
Kids need time, attention, stability, and parents who aren't stressed out about money. A lot of the "extras" actually work against that last one. The financial stress that comes from overspending often costs kids more than the stuff ever gave them.
The "Good Enough Parent" Money Rules
Here's how to get off the treadmill without feeling like a cheapskate:
Pick your "yes" categories. Choose one or two things your family truly values (maybe it's travel, sports, or music) and spend there without guilt. Then cut back everywhere else.
Set a birthday party budget, and stick to it. Decide the number before you start planning. A park, pizza, and a few friends is still a great party. Kids care about their friends, not the balloon arch.
Use the 48-hour rule. For any kid purchase over $100 that wasn't planned, wait 48 hours. Most "must-haves" disappear on their own.
Try "want, need, wear, read" for holidays. One thing they want, one they need, one to wear, one to read. It keeps gifts meaningful and your budget in check.
Let them earn the upgrades. Want the $180 sneakers? We'll cover what a good pair costs, and you can chip in the rest from your own money. Watch how fast priorities change.
Say it out loud: "That's not how our family spends money." It's a complete sentence. You don't owe anyone a longer explanation, including your kids.
Protect your savings first. Automate retirement and savings contributions before kid spending ever hits the budget. What's left is what you can spend guilt-free.
Scripts for Saying No
Saying no is hard, especially when it feels like everyone else is saying yes. Here are a few scripts that help:
To your kids:
"That's not in our budget right now. Let's figure out if you want to save up for it."
To other parents (when invited to the $400 group trip):
"That sounds amazing, but it doesn't fit our plans this year. Let's get the kids together another time!"
To grandparents (who love to overdo it):
"The kids would love the gift, but would you consider putting some toward their 529? It would mean a lot to us."
To yourself:
"My kids need me more than they need this."

Gif by HannahWitton on Giphy
Make It a Family Lesson
The most valuable thing you can teach your kids here is that your worth isn't measured by what you spend.
Talk openly about why your family makes the choices it does. Let older kids see the trade-offs: "We skipped the expensive camp, so we could take that trip together." When kids understand the why, they stop seeing "no" as punishment and start seeing it as a choice.
And you'll be raising kids who are much less likely to fall into the same comparison trap when they're adults.
The Bottom Line
Being a good parent was never about giving your kids everything.
It's about giving them what matters: your time, your attention, a stable home, and the example of someone who makes thoughtful choices with money. That example might be the most valuable inheritance you ever leave them.
So skip the bounce house if you want to. Your kids will be fine. And your future self will be very grateful.
A Message from Today’s Sponsor:
(Every click supports Knocked-up Money)
|
In partnership with 
|
Your Fall Glow-Up: Two Drinks for Hydrated, Plump-Looking Skin |
|
|
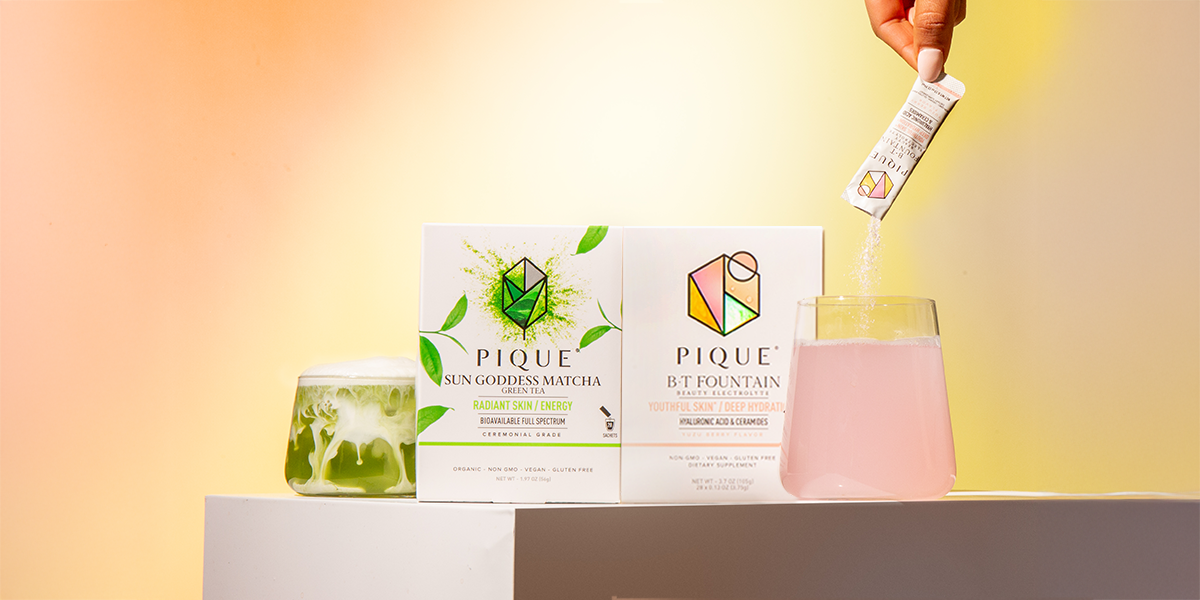
Cooler weather can leave skin looking dull and feeling dry. Pique’s Radiant Skin Duo brings a beauty upgrade to your fall routine: two delicious daily drinks that support hydrated, plump, luminous-looking skin from within. |
|
Start with creamy, organic Sun Goddess Matcha, packed with antioxidants that support healthy-looking skin. Then sip B·T Fountain, a refreshing beauty electrolyte combining clinically studied ceramides, hyaluronic acid and electrolytes to support hydration and a dewy glow. |
|
The beauty benefits come with impressive clinical evidence. In a clinical trial of B·T Fountain’s ceramides, skin hydration improved 25% by day 15. By day 60, hydration improved 37%, elasticity improved 36% and wrinkle depth decreased 8.2%. |
|
Morning matcha. Afternoon beauty hydration. An easy ritual that fits into busy fall days while supporting skin that looks smoother and feels replenished. Your favorite daily drinks become a simple skincare habit worth keep |
| Claim Your 20% Savings |
Thanks for reading today's newsletter! I hope it takes a little pressure off, because you're probably doing a lot better than you think.
Hit reply and tell me: what's the one "good parent" expense you've felt pressured into? Birthday parties? Travel sports? The holidays? I read every reply, and the best stories might make a future issue.
This newsletter is for educational purposes only and isn't financial, tax, or investment advice.
Which Money Topic Most Interests You?
📈 Investing
💰 Side Hustles
💼 Careers / WFH
💸 Ways to Save Money
🏦 Something Else – Reply With Your Thoughts
See you next week,
KMONEY
KMONEY Recommendations
I swear by this app. I use it for work and in my personal life. It takes notes while I can concentrate on the dialog which allows me to be present and focused.

